The Dominican Republic has gone from warning about Bitcoin and crypto-assets to incorporating them, directly and indirectly, into different layers of its legislation. There is still no comprehensive sector-specific digital assets law, but several tax, criminal, financial and anti-money-laundering rules can already reach certain activities related to them. This guide explains what applies today, to whom, and with what scope.
The essentials. The Dominican Republic does not yet have a comprehensive digital assets law, but that does not mean Bitcoin and crypto-assets are outside the legal framework. Several tax, criminal, financial and anti-money-laundering rules can already affect certain activities related to them.
This content is informational and does not constitute legal advice.
Is Bitcoin legal in the Dominican Republic?
No general prohibition on holding or transferring Bitcoin between private parties has been identified. Nor is Bitcoin legal tender: under Article 24 of Law 183-02, the Dominican peso is the only currency with the power to discharge debts, so no one is obliged to accept Bitcoin as payment.
It helps to distinguish between situations, because they are not treated the same way:
- Holding Bitcoin and transferring it between private parties: no general prohibition has been identified.
- Accepting it at a business: no one is obliged to take it; the treatment may vary if a regulated payment or financial service is involved.
- Providing payment services: there are specific restrictions for certain authorized categories within the payment system.
- Regulated financial activities, such as taking funds from the public with a promise of return: these may require prior authorization, regardless of the asset used.
- Operating an exchange or holding third-party assets in custody: no sector-specific licensing regime has been identified, which is not the same as an authorization.
That no general prohibition has been identified does not mean Bitcoin is authorized for any activity. The treatment depends on what is being done, not only on the asset.
This explanation is informational and does not replace professional legal advice.
A distinction worth making from the outset
The most repeated phrase about crypto-assets in the country — that they are not regulated — turns out to be imprecise when checked against the available documents.
Two things that are often mixed up should be kept apart. One is sector-specific regulation: a law designed for digital assets that defines categories, creates licenses, assigns a supervisor and sets obligations for platforms. That does not exist as of August 19, 2026. The other is the set of general rules already in force that, without having been written for this sector, can reach it depending on the specific activity involved.
Regulatory timeline
- June 27, 2017The Central Bank publishes its first communiqué on virtual currencies. It expressly mentions Bitcoin, Litecoin and Ethereum and warns that it does not regulate or supervise these assets.
- September 30, 2021The Central Bank reiterates and expands its position: crypto-assets are not legal tender and have no power to discharge debts, and regulated entities are not authorized to operate with them within the Payment System.
- October 2021 – October 2023The tax authority (DGII) sets its criterion in at least four technical rulings: income derived from cryptocurrency transactions constitutes taxable income.
- August 3, 2025Law 74-25, the new Criminal Code, is enacted. Its Article 240 expressly mentions cryptocurrencies, tokens and NFTs within the offense of pyramid fraud. Published in Official Gazette No. 11208.
- August 28, 2025The Monetary Board approves the comprehensive amendment of the Payment Systems Regulation (Resolution JM 250828-02), which defines “virtual asset” and sets restrictions on certain payment-system participants.
- June 18, 2026Law 30-26 is enacted. Its Article 19 expressly incorporates “digital goods and crypto-assets” into the Tax Code’s definition of capital asset.
- August 2026The Criminal Code enters into force. The two sector-specific bills remain without a committee report in the Standing Committee on Finance since June 8.
Regulatory map of crypto-assets in the Dominican Republic
| Area | Authority | Crypto mention | Impact |
|---|---|---|---|
| Payment systems | Monetary Board / BCRD | Yes, express | High |
| Taxation | DGII | Yes, express | Medium-high |
| Criminal | Criminal Code 74-25 | Yes, express | Medium |
| Securities market | SIMV | Depends on the asset | Variable |
| Anti-money-laundering | UAF | Not by name | Indirect |
| Consumer protection | Pro Consumidor | Not by name | Tested |
| Monetary and financial | Law 183-02 | No | Depends on activity |
The individual explanations for each area are developed in the following sections.
Who regulates what
Central Bank / Monetary Board
- Role
- Monetary system and payment systems.
- Crypto
- Defines “virtual asset” and sets specific restrictions on certain regulated participants.
- Impact
- High on payment infrastructure.
DGII (tax authority)
- Role
- Taxation.
- Crypto
- Capital gains and tax treatment of crypto-assets.
- Impact
- Direct on taxpayers.
Criminal Code
- Role
- Criminal conduct.
- Crypto
- Express references within certain offenses, mainly fraud.
- Impact
- Aimed at fraudulent conduct.
Securities market
- Role
- Public offerings, securities and financial instruments.
- Crypto
- Potential application depending on the legal and economic nature of the token.
- Impact
- Variable.
Anti-money-laundering
- Role
- Compliance on money laundering and terrorist financing.
- Crypto
- May be relevant depending on the activity and obligated-entity status.
- Impact
- Indirect, via financial institutions.
Consumer protection
- Role
- Adhesion contracts and commercial practices.
- Crypto
- General jurisdiction already exercised over a project in the sector.
- Impact
- Demonstrated in court.
Regulatory status of Bitcoin and crypto-assets
This traffic-light summary is an editorial synthesis by CriptoDominicano prepared from the regulatory framework identified in this research. It is not an official classification by the Dominican government or any regulator, and the colors do not express authorization, license or endorsement by any authority: they only indicate the degree of regulatory clarity we found in each case.
Payment systems: the Regulation of August 28, 2025
It is probably the least publicized piece of the Dominican regulatory picture. On August 28, 2025, through the Second Resolution of the Monetary Board (JM 250828-02), the comprehensive amendment of the Payment Systems Regulation was approved.
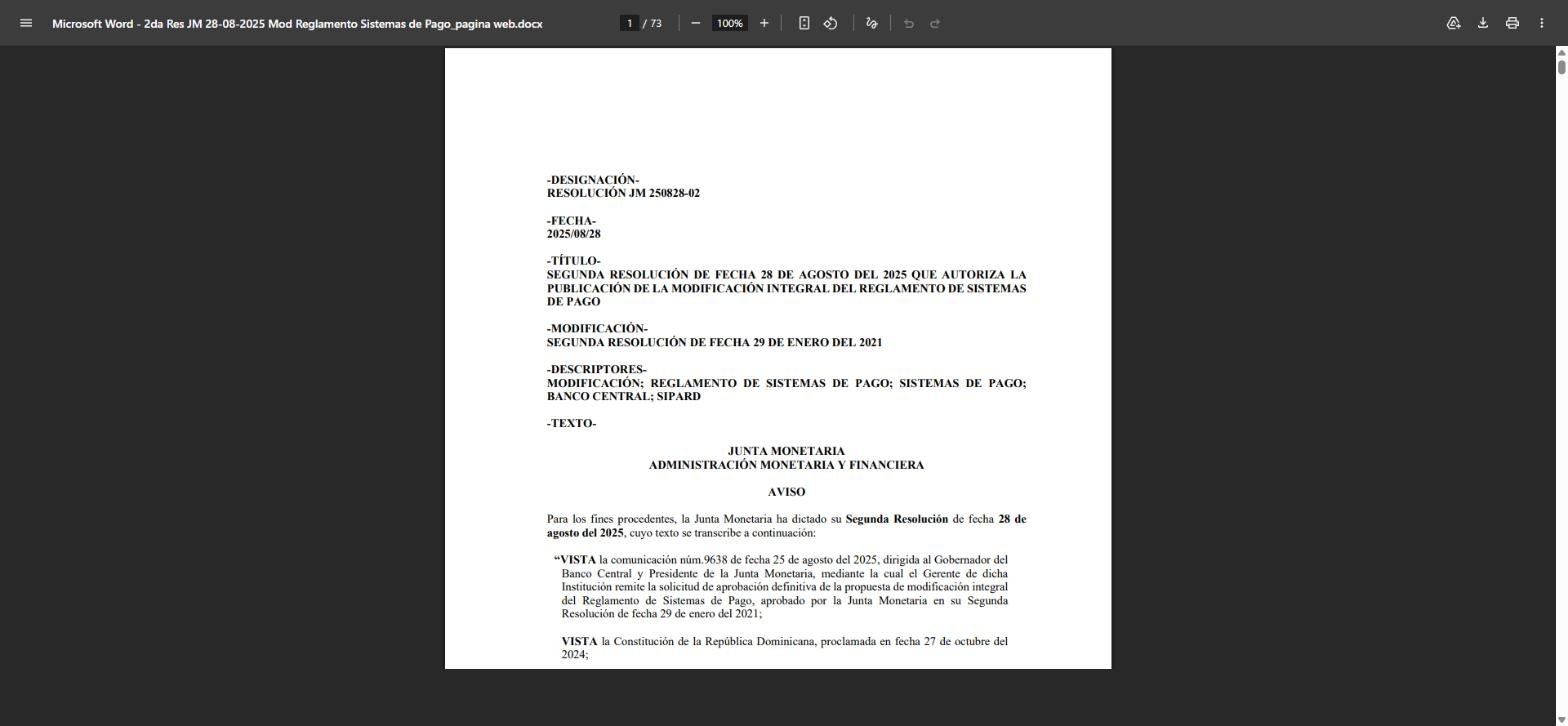
Article 4, subparagraph a) — Virtual asset:
“Digital representation of value that can be traded or transferred digitally and used for payment or investment purposes, without legal tender in the national territory, foreign currencies or any other asset being understood in any case as a virtual asset;”
Source: Monetary Board / Central Bank of the Dominican Republic — Payment Systems Regulation, August 28, 2025. Article 4, subparagraph a), pages 9-10 of the official PDF.
The definition is broad as to its object — any digital representation of value that is tradable or transferable and used for payment or investment — but it incorporates a triple exclusion: legal tender in the national territory, foreign currencies and any other asset are not considered virtual assets. That last exclusion narrows the concept and should not be omitted when citing the rule.
Alongside the definition, the regulation incorporates two identically worded prohibitions, addressed to two different categories of participants.
Article 11, subparagraph v) — obligations of the administrator of a payment or securities settlement system, and Article 17, subparagraph w) — obligations of the electronic payment entity. Both provide, in identical terms:
“Not offer products or services based on virtual assets;”
Source: Monetary Board / Central Bank of the Dominican Republic — Payment Systems Regulation, August 28, 2025. Article 11, subparagraph v), page 26; Article 17, subparagraph w), page 32 of the official PDF.
These subparagraphs impose the prohibition specifically on the regulated categories indicated: administrators of payment or securities settlement systems (Article 11) and authorized electronic payment entities (Article 17). On their own, they do not establish a general prohibition applicable to every bank, exchange, custodian, business or end user. The obligations of those categories must be analyzed under the other rules applicable to them:
- Banks and financial intermediation entities: they are not among the addressees of these two subparagraphs in particular. That does not prejudge their situation, which will depend on the rest of the framework applicable to them, including the monetary and financial regime and anti-money-laundering rules.
- Exchanges and custodians: the regulation does not create a virtual asset service provider figure, so they do not appear as a category of their own. The scope will depend on whether the entity falls within any of the regulated categories of the payment system, and on the other tax, criminal, anti-money-laundering or securities rules that may apply to it.
- Businesses and end users: they are not among the addressees of these subparagraphs, which are aimed at authorized payment-system participants. Their obligations, if any, must be analyzed under other rules, notably tax and consumer-protection rules.
The same regulation created new figures — digital wallet provider, payment initiation service provider, payment gateway, sub-acquiring and cross-border acquiring — and set minimum capital requirements: RD$75,146,000.00 for a system administrator or an acquiring company and RD$18,790,000.00 for an electronic payment entity. It also introduced testing environments (sandboxes) for payment services; it could not be determined whether they admit use cases based on virtual assets.
What does this mean in practice?
For a Bitcoin user
For a business
For a fintech
For an exchange
For a custodian
Taxation: Law 30-26 and the DGII’s earlier criteria
Law 30-26, Article 19, which amends subparagraph e) of Article 289 of the Tax Code:
“Capital asset. The concept of capital asset means any property, including digital goods and crypto-assets, held by the taxpayer whether or not in connection with their business.”
Source: Presidency of the Republic — Law No. 30-26, enacted June 18, 2026. It is the only mention of crypto-assets in the law’s 62 provisions.
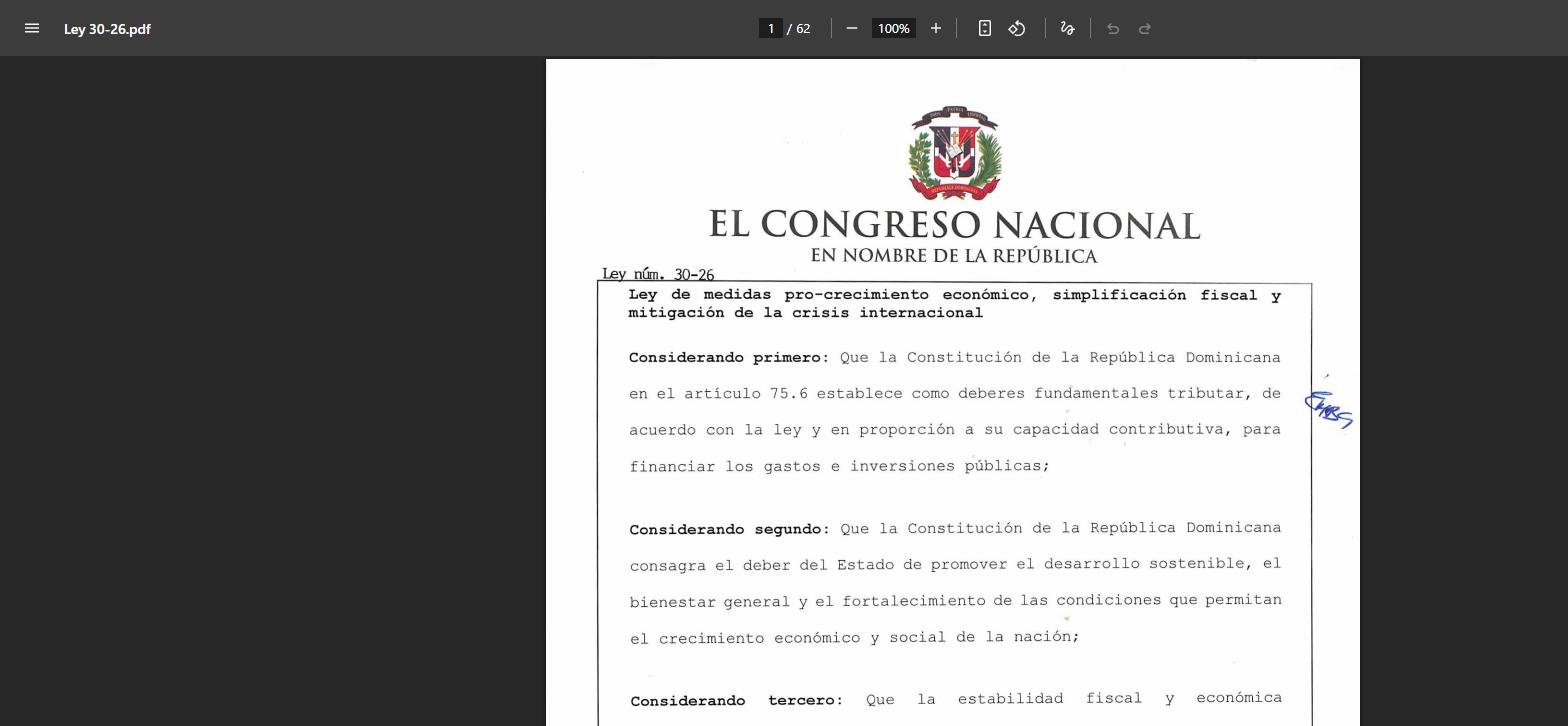
It would be imprecise to present that reform as the origin of crypto taxation in the country. The DGII had been maintaining an equivalent criterion since October 2021, in at least four technical rulings — that of October 13, 2021, Ruling 6 of December 23, 2021, Ruling 40 of May 25, 2022 and Ruling 20 of October 10, 2023 — relying on Articles 267 and 268 of the Tax Code, in force since 1992.
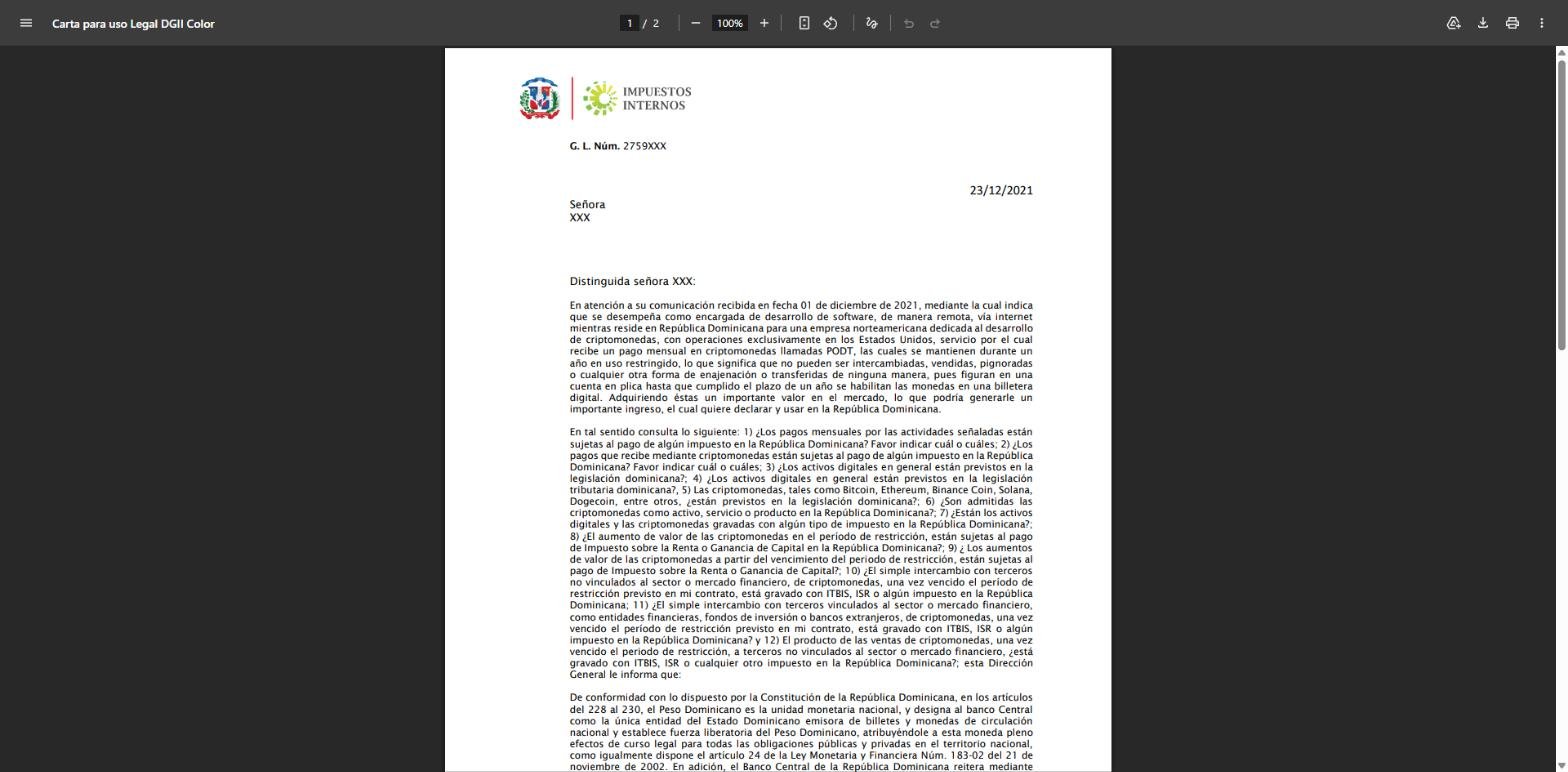
What Law 30-26 contributes is of a different order. First, enforceability: a technical ruling binds, in principle, the party that requested it; a legal text applies generally. Second, systematic placement: the treatment now sits in the chapter on capital gains and losses, which under the text in force would allow consideration of the inflation adjustment of cost provided for in Article 327 and the carry-forward of losses against future gains. Third, it closes the discussion over whether a crypto-asset fit within the catalog of taxable property.
One point to bear in mind: if the crypto-asset constitutes inventory or property intended for ordinary sale — the case of someone who trades habitually — it would fall outside the concept of capital asset under Article 289’s own exclusions, and its treatment would be that of ordinary income.
Still open: when is a gain considered realized in a crypto-to-crypto swap?
Article 289 defines a capital loss as one arising from “the sale, exchange or other act of disposal” of a capital asset, and its Paragraph I understands disposal as “any transfer inter vivos of ownership of property, whether gratuitous or for consideration.”
First reading. The exchange of one crypto-asset for another, without conversion into pesos, would constitute a taxable event.
Second reading. The administrative criterion expressed by the DGII in its rulings ties the tax to conversion into “money valid and recognized in the country.”
These are two different readings of the moment at which the gain materializes. Absent a specific pronouncement by the regulator reconciling them, the question remains open and may require further administrative clarity or case-by-case professional interpretation.
What secondary regulation has yet to develop
As of the close of this review, no general rule, resolution, instruction or form from the DGII referring specifically to crypto-assets after Law 30-26 was identified. The three rules put out for public consultation through Notice 11-26 — tax amnesty, accelerated depreciation and tax treatment of software — do not address the matter. DGII Notice 10-26, the official implementation calendar for Law 30-26, details the staggered entry into force of each measure of the reform and does not mention Article 19, Article 289, digital goods or crypto-assets.
Still to be specified, among other aspects: the rate applicable to capital gains of individuals — the flat 10% rate created by the same law literally refers to real estate — valuation rules and the price source, the moment of realization, substantiation of tax cost, the treatment of mining, staking, airdrops and forks, the application of ITBIS (VAT) to related services, and the source criterion for non-residents.
Criminal regulation: Criminal Code 74-25
Law No. 74-25, the Organic Law establishing the Criminal Code, was enacted in August 2025 and published in Official Gazette No. 11208 of August 5, 2025. The Presidency’s official record lists August 4 as the date of enactment, while other references indicate the 3rd. Under its Article 393 it entered into force twelve months later, a date over which there was public disagreement between the Executive Branch’s Legal Counsel and the Attorney General’s Office.
Article 240 — pyramid fraud (excerpt):
“…aim to recruit persons from whom they obtain money, digital assets such as: cryptocurrencies, tokens, NFTs or digital documents with financial value, making them false promises of returns on their investments, without the existence of a legitimate, duly authorized business of goods or services or investments…”
Source: Presidency of the Republic — Law No. 74-25, Official Gazette No. 11208 of August 5, 2025.
The provision is part of a broader section on fraud, with penalties scaled according to severity and the role of each participant.
The penalty is 5 to 10 years and a fine of one to twenty times the amount involved. Article 241 raises it to 10-20 years with aggravating circumstances, among them the use of digital platforms and social networks; Article 242 reaches intermediaries, promoters and brokers with 3 to 5 years; and Article 243 separately criminalizes habitual financial intermediation without authorization from the monetary or securities-market authorities, with 5 to 10 years. On July 27, 2026, Law 44-26 amended 27 articles of the Code before its entry into force; according to the available analyses, Articles 240 to 242 were not among them.
These offenses are aimed at fraudulent conduct. The mention of cryptocurrencies in the Criminal Code does not turn their ordinary use into a crime. For the industry, Article 243 may be as relevant as Article 240: a product that takes funds from the public with a promise of return — lending arrangements, yield products or staking services offered with guaranteed returns — could fall within the concept of financial intermediation, depending on its structure.
It is worth recalling that, before the Code named them, Dominican courts had already convicted schemes of this kind. The Harvest Trading Cap case ended with a sentence of 5 years and RD$25 million in February 2025.
Anti-money-laundering: where the sector stands
Virtual asset service providers do not appear on the list of obligated entities published by the Financial Analysis Unit (UAF) under Law 155-17. That list comprises banks, securities intermediaries, exchange agents, trust companies, cooperatives, insurers, casinos, real-estate agents, lawyers, accountants, notaries, pawnshops and construction companies.
That does not place the sector outside the system. Article 34 requires obligated entities to cover in their compliance programs the products and channels “that use new technologies,” so the financial institution serving a platform is indeed covered and the risk burden can be shifted through that route. Moreover, money laundering is a stand-alone offense, applicable regardless of the instrument used.
In GAFILAT’s Mutual Evaluation Report, the Dominican Republic received a “C” — compliant — rating on Recommendation 15, on new technologies. That report dates from September 2018, and the FATF amended Recommendation 15 in October 2018 precisely to incorporate virtual assets and their providers. The rating therefore refers to the earlier standard.
Securities market: when a token could be a security
Law 249-17, Article 3, item 41 — Security:
“A right or set of rights of essentially economic content, which incorporates a literal and autonomous right exercised by its legitimate holder.”
Source: Securities Market Superintendency — Law No. 249-17 on the Securities Market.
The definition is functional and does not require any particular documentary form. One possible interpretation is that a token conferring economic rights — dividends, profit sharing, debt or participation in a business managed by third parties — could fall within that definition, depending on its structure, and that offering it to the public would require prior authorization from the SIMV. Item 31 defines public offering broadly, and Article 48, Paragraph I, empowers the agency to classify an unauthorized offering as a public offering and order its suspension. A payment asset such as Bitcoin, which incorporates no right against an issuer, would not fit that definition. It was not possible to verify whether the SIMV has issued specific criteria on crypto-assets, token offerings or tokenization.
Consumer protection: a precedent already applied
The most concrete example of the application of existing Dominican law to a digital asset project did not come from a financial regulator. On November 14, 2024, Pro Consumidor ordered, through Act No. 1840-24, the suspension of Worldcoin Foundation’s operations in the country. On December 12, Resolution 2058-24 prohibited the use of its terms and conditions and its privacy statement. The grounds invoked were Consumer Protection Law 358-05, the resolutions on adhesion contracts and Personal Data Law 172-13, over the collection of biometric data. The company appealed and, on February 26, 2025, the Superior Administrative Court rejected its request for interim relief and confirmed that Pro Consumidor has legal authority to act.
VASP license: what was sought and what was found
According to the research conducted and the official sources identified, the Dominican Republic does not currently have a comprehensive sector-specific licensing regime for virtual asset service providers equivalent to the VASP models existing in other jurisdictions.
It is worth being precise about what that means and what it does not. It means that no specific authorization path before a given authority, with its own requirements, procedure and supervision, was located. It does not mean that any exchange can operate freely, that no other obligations exist, or that tax, criminal, anti-money-laundering, securities-market or payment-system rules cease to apply. The absence of a sector-specific license is not equivalent to authorization, just as it is not equivalent to prohibition.
A company in the sector can incorporate under Law 479-08, obtain its RNC (taxpayer registration) and meet its tax obligations without that amounting to an authorization of its activity, because those are different things. Nor was any sector-specific framework identified on custody of digital assets, segregation of client funds, capital requirements for platforms, stablecoins, prudential treatment, the travel rule, or specialized dispute-resolution mechanisms against platforms without a domicile in the country.
The bills in Congress and the case before the Constitutional Court
Two initiatives seek to close that gap. 05400-2024-2028-CD, “Bill on the prevention, control and regulation of cryptocurrencies,” filed on March 16, 2026 by Deputy Carlos de Pérez Juan; and 05569-2024-2028-CD, “Bill on digital assets and crypto-assets,” filed in April 2026 by Deputy Jorge Frías, who passed away on August 7, 2026.
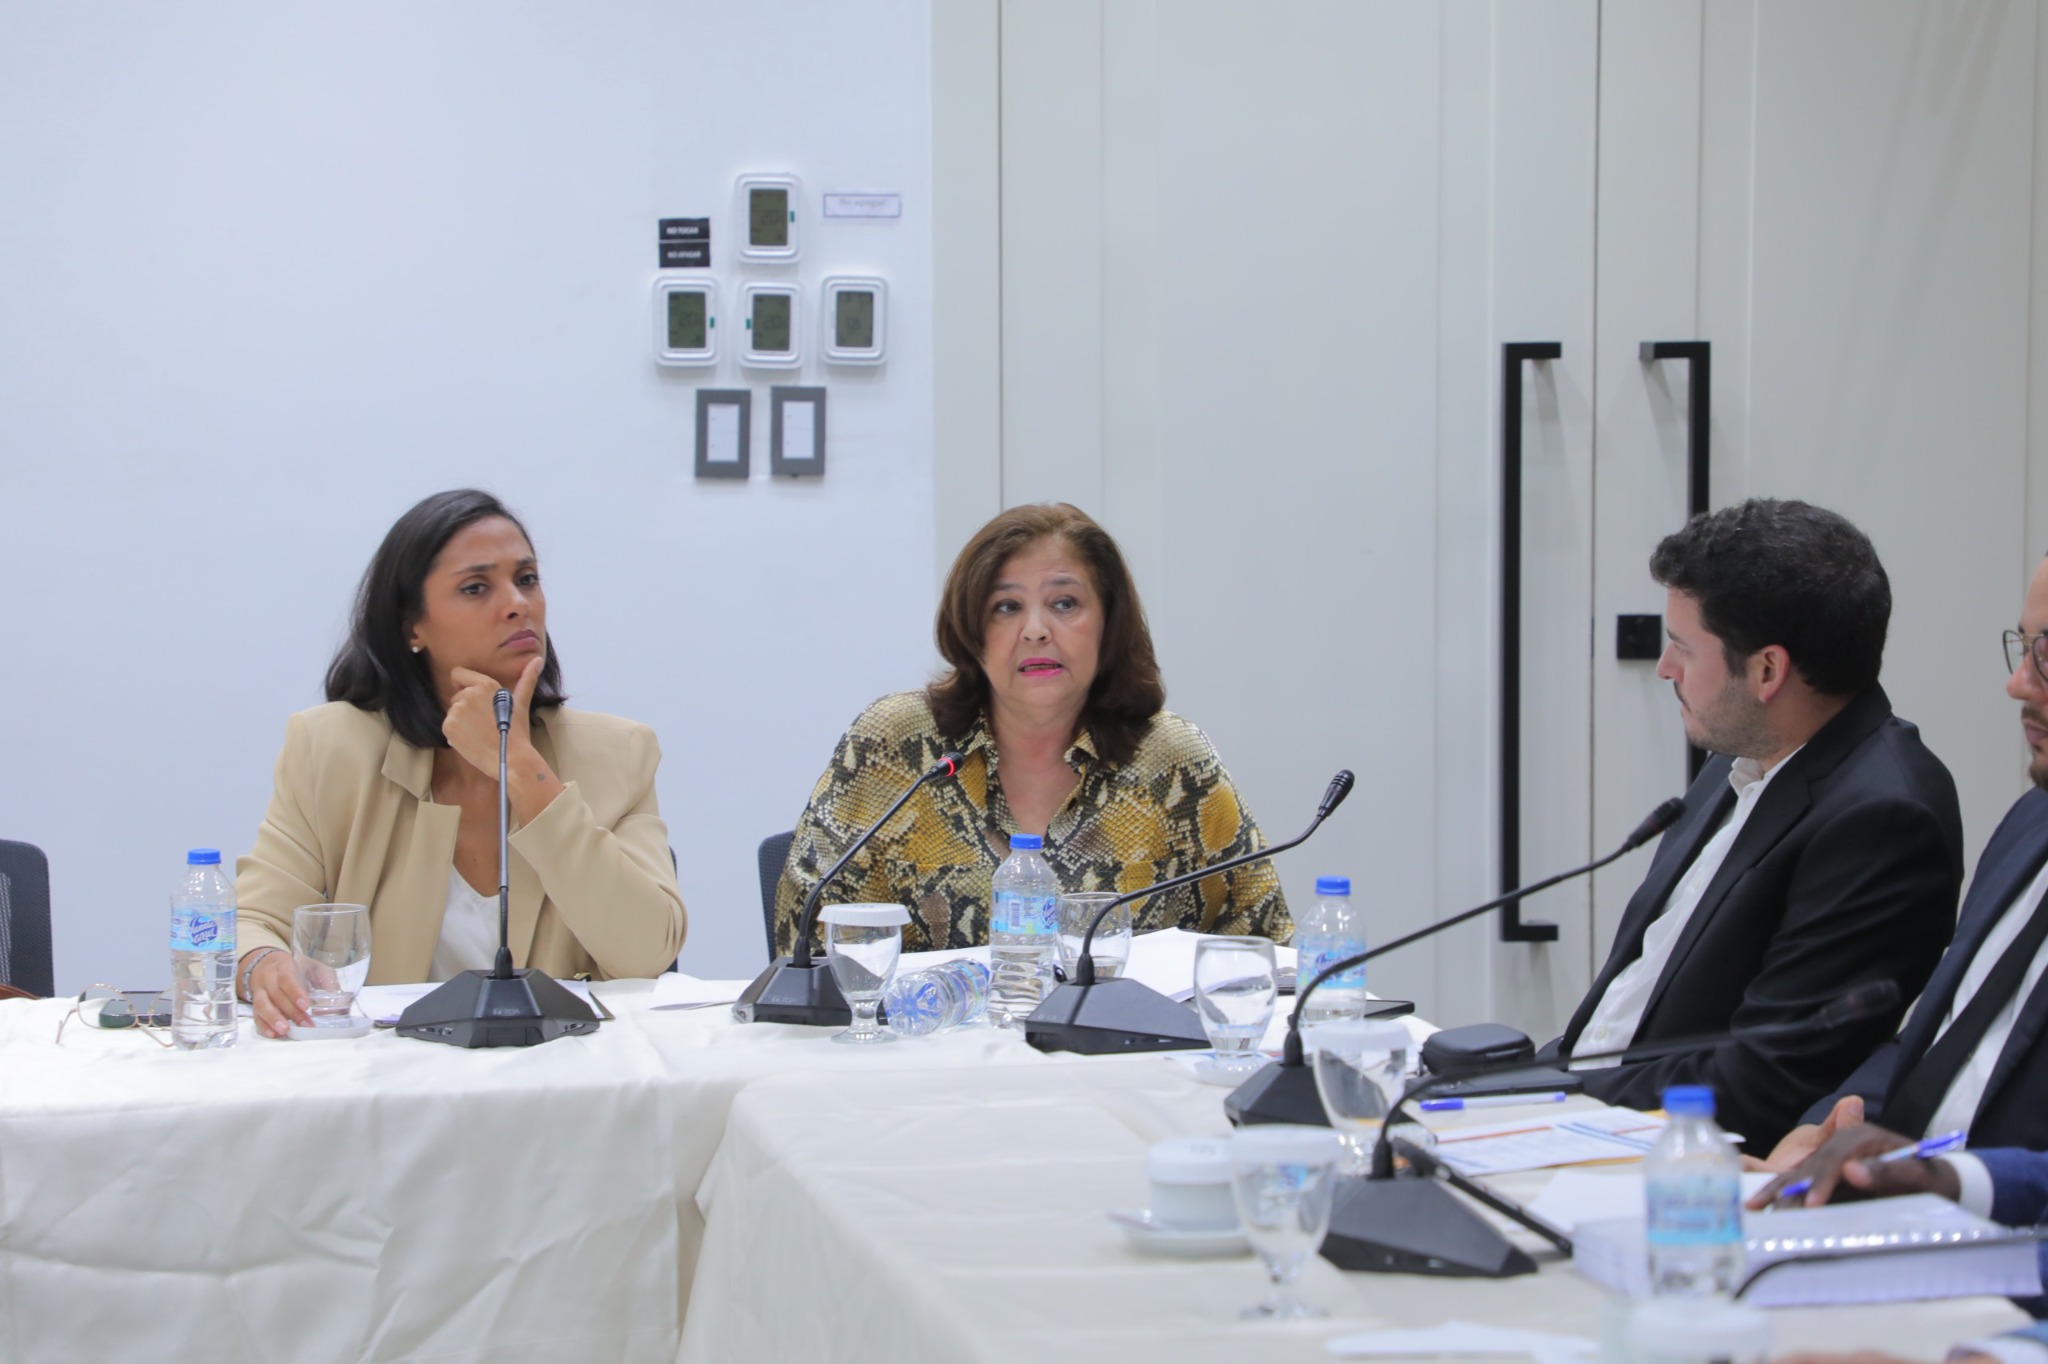
The Standing Committee on Finance held two technical hearings, on May 28 and June 8, with the participation of Finlabs, Tether, Grupo Multicómputos, NEITEC, the Asociación de Bitcoin Dominicana, the Bitcoin RD platform and compliance specialists. At the second, the Committee’s president, Francisco Javier Paulino, publicly reported that both bills had been merged for study and announced that opinions would be requested from the Central Bank, the Superintendency of Banks and the DGII. No public committee minutes were located to specify the procedural scope of that merger, nor public evidence that the requests were sent. No session has been convened since then, and the regulatory study deadlines expired in May without a committee report.
On the validity of the files: Article 104 of the Constitution — not Article 103, which governs the deadline for considering observations from the Executive Branch — provides that bills pending at the close of an ordinary legislative session “shall continue the constitutional procedures in the following session, until they are enacted into law or rejected.” Under that text, the close of the session on July 26, 2026 would have consumed the first of the two sessions, and lapse would occur at the close of the current session, scheduled for January 12, 2027.
In parallel, on December 18, 2025, Marino Marrero Báez filed before the Constitutional Court a direct action of unconstitutionality against the National Congress for “legislative omission in the matter of virtual assets,” case file TC-01-2025-0073. The Court placed it in pending-judgment status on April 22, 2026 and, as of the close of this article, had not issued a ruling. There is a relevant procedural precedent: in October 2024, through judgment TC/0487/24, the Court itself modified its earlier precedent and held that absolute legislative omissions are not within the scope of the direct action of unconstitutionality. It is not appropriate to anticipate the outcome of the ruling.
Conclusion
The diagnosis supported by the available documentation is more nuanced than the usual phrase. In the Dominican Republic, crypto-assets are not beyond the reach of the law: they are covered indirectly and in fragmentary fashion by rules written for other purposes. There is a regulatory definition of virtual asset in the field of payment systems, restrictions on certain participants in that system, criminal offenses applicable to fraudulent conduct, a taxable event recognized in the Tax Code, administrative jurisdiction already exercised in consumer matters, and a concept of security broad enough to encompass certain tokens.
What was not identified is an authorization path: a regime under which a virtual asset service provider can apply for a license, submit to supervision and operate under clear rules. Describing precisely what does exist is probably the best argument in favor of a sector-specific framework: what is missing is not applicable law, but a coherent framework to organize what is currently scattered.
Key documents
This content is informational and does not constitute legal, tax or financial advice. The readings indicated as possible correspond to this outlet’s analysis and not to a decision by any Dominican authority. For a specific situation, it is advisable to consult a professional. Quotations from Dominican legal texts are our own translations from the Spanish originals; this is an English adaptation of our Spanish-language report.
For an explanation focused specifically on Bitcoin, self-custody, payments and adoption, see the analysis published by Bitcoin Dominicana (in Spanish).


